
The OXUS Tajikistan Women Client Study: Listening to rural women borrowers in Central Asia
Most importantly, the leonardo team took time to walk us through the "why" behind the numbers, giving us a clear understanding of the results.
Vatansho Vatanshoev, CEO of OXUS Tajikistan (OTJ)
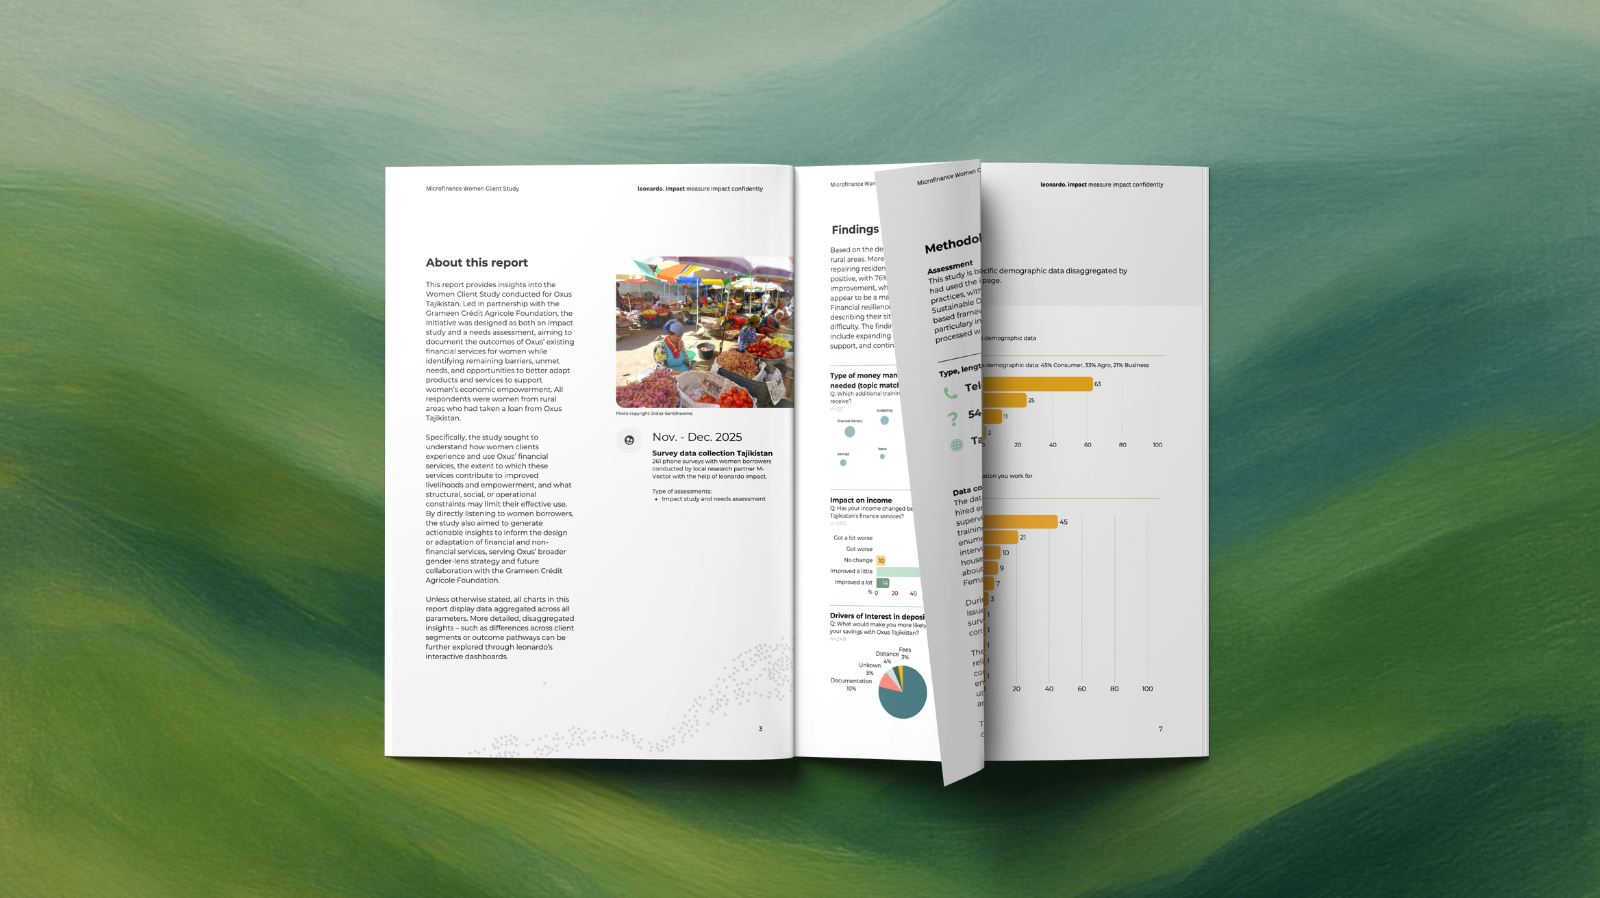
That commitment to understanding the "why" captures the ambition behind this study. We wanted to know how OTJ's loans actually change what's possible for rural women, and what still stands in the way. We're publishing the OXUS Tajikistan Women Client Study, conducted in partnership with the Grameen Crédit Agricole Foundation (GCAF), OTJ's investor and impact partner, and delivered with local research partner M-Vector. Between November and December 2025, we listened to 261 women borrowers across rural Tajikistan to understand how OTJ's loans affect income, well-being and women's agency, and what unmet needs remain.
What the study found
The data shows a portfolio that meaningfully supports women's livelihoods, with clear opportunities to broaden its offering:
- Income improvements are the norm. 90% of women report improved income from OTJ's services. 89% find repayment easy or very easy, well above the Asia benchmark of 78%.
- Financial resilience is a real strength. 79% of women could cope with a large unexpected expense, far above the 28% global benchmark for women microfinance clients.
- Confidence is rising. 94% of women report increased confidence in making financial decisions independently since using OTJ's services.
- Latent demand for savings is significant. 89% of women have no savings account, yet 82% would open one with OTJ. Trust in OTJ (78%) is the leading reason.
- Household finances are shared. In rural areas, women typically decide loan use jointly with other household members (65%), and over half share repayment responsibility, reflecting Tajik household norms where discussing and managing finances together is common.
Download the full Microfinance Women Client Study here for deep analysis, methodological notes, and the full set of charts.
Who took part
The study reached 261 women clients across OTJ's regions of operation: 80% rural, 20% urban, with 228 household representatives, 25 business owners and 8 individual borrowers, most aged between 18 and 45. The sample reflects OTJ's consumer-heavy portfolio (63% Consumer, 25% Business, 11% Agro), with residential housing repair, health treatment, tuition fees and clothing among the most common loan purposes.
How the data was collected
The 54-question survey follows recognised scientific standards, with indicators aligned to the SDGs, the CGAP Women's Economic Empowerment framework and the Global Findex. Enumerators from M-Vector, trained by leonardo and supervised by Alexandra Zhumanalieva, conducted telephone interviews in Russian and Tajik. All responses flowed into leonardo's Impact Management Platform (IMP), where an AI-powered data quality audit assessed representativity, consistency and integrity before findings were finalised.
Working with leonardo has been a 10/10 experience. The research outcomes have proven valuable for our partners, providing them with actionable insights directly informing their strategic decisions, budget allocations, and action plans.
Maya Azcona, Technical Assistance Program Officer at GCAF
The way forward
At the end of 2025, OTJ transformed into a micro-deposit organisation, a change that meets its clients where they already are. 82% of women in the study want to save with OTJ, citing trust as the reason, yet 89% currently have no savings account anywhere. Rolling out small-balance, accessible savings products is the most direct route to convert this demand into real financial security. Light-touch financial education focused on budgeting and business management (the topics women themselves requested) would complement the product expansion. Operationally, reviewing late-payment penalty structures, aligning repayment schedules with rural income cycles, and continuing to expand the network of female credit officers (72% of women prefer same-gender officers) would address the small friction points identified in client feedback and protect the already high Net Promoter Score of 56.20.
Read the full story
For the longer narrative behind this partnership, including how the study was designed and the cross-country findings, read our case study: Assessing microfinance outcomes for women: A practitioner's approach to client needs in Central Asia.
The OXUS Kyrgyzstan impact report follows the same methodology and shows how outcomes differ across the region. Explore the findings here.
Get to know Grameen Crédit Agricole Foundation and OXUS Tajikistan and support their amazing work.
Want to know more?
Get in touch with us and and start to measure impact confidently.